
Inside The Deal Room: Six Recently Funded Deals
A snapshot into six completed deals - and what they say about what’s actually getting funded right now
As we approach the end of Q3 and the last quarter of 2026, I thought it might be useful to share with you some of the funding deals we’ve completed in the last few months. I know many of you reading this are likely going to require debt to execute your business plans in 2027, and the good news is that the debt markets remain open. However, it’s super important that you understand the process, who’s lending, and at what cost, before you agree to any kind of facility.
Numbers and market commentary only tell half the story. The other half is what’s actually happening on the ground: the deals being structured, the lenders saying yes, and the terms clients are achieving in the current market. Here’s a snapshot of six facilities we’ve worked on recently right through to completion, spanning residential development, specialist acquisitions, unsecured working capital, and commercial investment.
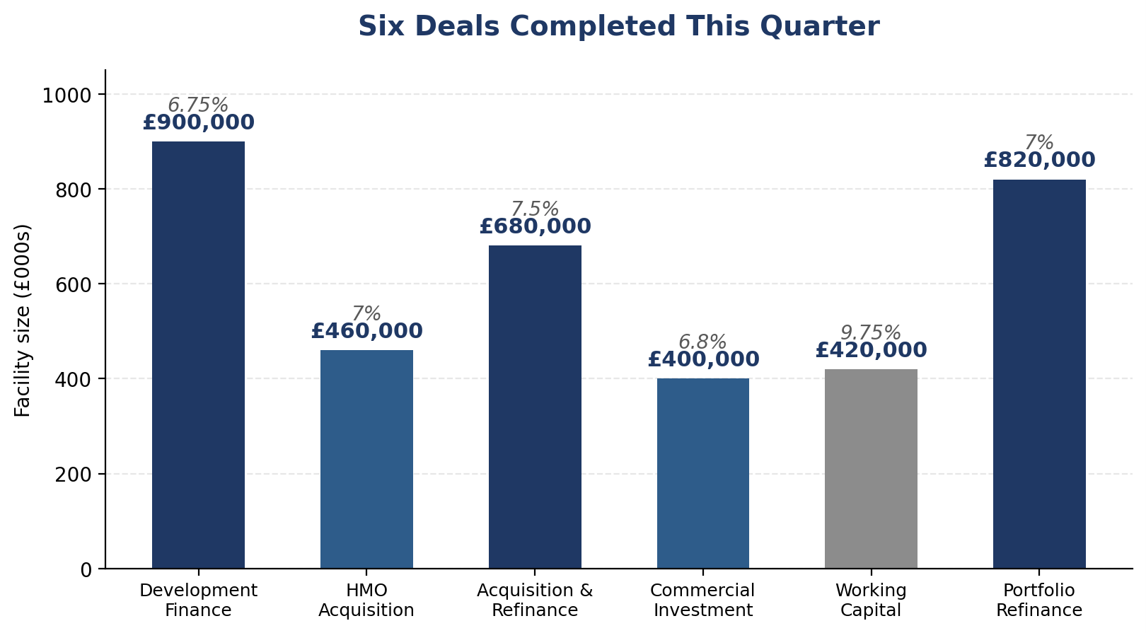
Facility size and pricing across the six deals featured below
1) Development Finance - Co. Down £900,000 | Local bank | 6.75%
A development loan facility for a residential scheme in Co. Down. Mainstream bank appetite for well-structured residential development remains solid when the numbers stack up. We placed this one with one of the local banks on the square, whom we have a great relationship with, and by working together, we can get the funding turned around quickly. Pricing came in at a competitive 3% over base.
2) HMO Acquisition - Co. Down £460,000 | Technology bank | 7%
Acquisition funding for a house in multiple occupation (HMO) in Co. Down, secured on a 5-year fixed rate. HMO stock remains one of the more specialist asset classes to fund. Licensing, management structure, and valuation approach all add complexity that most mainstream lenders price for accordingly. Given our unique understanding of all that is involved here, we were able to ensure the finance was delivered promptly and on time.
3) Acquisition & Refinance - Co. Antrim £680,000 | Local bank | 7.5%
A combined acquisition and refinance facility for a Co. Antrim client, consolidating existing borrowing onto cleaner terms while funding a new asset addition in the same structure, rather than running two separate facilities side by side.
4) Commercial Investment - Derry £400,000 | Local bank | 7.25%
Investment funding secured against commercial premises in Derry, priced at 7.25% over a 15-year term. Long-dated, affordable terms like this are typical of quality income-producing commercial stock in the current market.
5) Working Capital - Unsecured £420,000 | Unsecured lender | 9.75%
An unsecured working capital facility placed with one of our most productive unsecured lenders. A reminder that alternative and fintech lenders remain a legitimate, fast-turnaround option sitting alongside bank finance, particularly useful where speed matters more than the lowest possible rate.
6) Portfolio Refinance - Co. Down £820,000 | Local Bank | 7%
Refinance of an existing property portfolio in Co. Down through another local bank. More evidence that mainstream banks remain active and competitive on refinancing seasoned, well-performing portfolios.
What This Says About the Market
Taken together, these six deals cover quite a bit of what we do at GDP and Clearpath Finance: mainstream residential development, specialist HMO and portfolio lending, commercial investment finance, and unsecured working capital. The common thread isn’t the asset class or the lender; it’s that each facility was structured around what the client actually needed, not just what was easiest to arrange.
That’s the real advantage of working with GDP: our job isn’t just finding a lender who’ll say yes, it’s finding the cheapest money available for the deal in front of us, and getting it turned around quickly.
Too many business owners get bogged down in a bank process that often drags on for months, chasing paperwork and waiting on credit committee decisions, without ever questioning whether that’s the best they can do. Time is money, and a slow, drawn-out process doesn’t just cost patience—it costs opportunities, and often the deal itself. Working with someone who knows the market and the lenders well enough to move fast is rarely the expensive option; it’s usually the one that saves the most.
If you’re weighing up a deal of your own, whatever stage it’s at, that’s exactly the conversation worth having early.
If you need some help with this, I would be delighted to hear from you.
All the best,
Conor
GDP Partnership | Debt Advisory & Business Finance | Belfast