
The Banks Are Back: Northern Ireland's high street lenders are profitable, well capitalised and out looking for business again
For the best part of three years, the conversation with most business owners about bank finance went the same way. The bank was making record profits, but the answer to a new facility was slow, cautious or simply no. Since 2016, when we started our bridging business, Clearpath Finance, most deals and businesses we were seeing were being pushed towards private credit and bridging lenders, which proved much more costly.
That trend has changed undoubtedly over the last couple of years, and it’s very clear that the mainstream banks are back in the market, and they want to lend.
The numbers tell the story
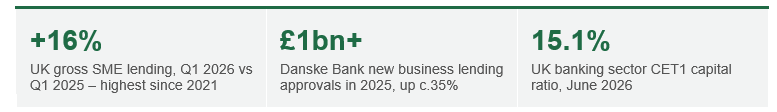
UK Finance figures show gross lending to SMEs reached £5.3 billion in the first quarter of 2026, up 16% on the year before and the highest level since 2021. New loan approvals rose 36% by value and 42% by number.
Closer to home, Danske Bank, Northern Ireland's largest lender, approved more than £1 billion of new business lending in 2025, up around 35%. It added over £400 million of approvals in the first half of 2026, and its total loan book grew 10%.
Why now: profit and capital
Banks lend when they have two things: earnings to absorb risk and capital to back new loans. Right now, they have plenty of both.
Profits are strong. Danske Bank UK made £250 million before tax in 2025, about £1 million every working day, and £135 million in the first half of 2026, up 14%. NatWest Group, which owns Ulster Bank, reported £4.3 billion of operating profit in the first half. Bank of Ireland’s half-year Group profits rose 33% to €960m.
Capital is plentiful. The UK banking sector's core capital ratio stands at 15.1%. In December 2025, the Bank of England lowered its benchmark for how much capital banks need to hold, with the stated aim of supporting lending and growth.
Deposits are sitting idle. Danske Bank UK holds £12.5 billion of customer deposits against £7.3 billion of loans. That is a lot of money waiting to be put to work.
What we are seeing on the ground
The numbers match what we see every week. Relationship managers and business development teams are back out on the road, picking up the phone and asking for introductions. Credit committees are moving faster, and banks are competing on terms again in a way we have not seen for some time. This is hugely significant, and for me, you would have to go back to before 2008 to compare a time when banks were as active in the local marketplace.
For borrowers, that means choice. And where there is choice, there is leverage on pricing, fees, covenants, and security.
A word of caution
Not every bank is chasing the same business. Bank of Ireland, for example, says it is prioritising “value over volume” in the UK, and its UK lending fell in the first half. Appetite varies by lender, by sector, and by deal size. The best terms still go to the business that approaches the right lender with a well-prepared, well-presented case.
What should you do now?
Go back to the banks. If you were turned down in the last two or three years, the answer may well be different today.
Review expensive debt. Private credit or bridging finance taken on when the banks were effectively closed may now refinance onto cheaper mainstream terms.
Move before Christmas. Lenders slow down from late November. Facilities needed for the new year should be agreed now.
Get the case right. Up-to-date accounts, management information, and a clear cash flow forecast make the difference between a quick yes and a long process.
The window is open. At GDP Partnership, we know which lenders are hungry, for what, and on what terms. If you are thinking about new funding or refinancing, talk to us before you talk to the bank.
At the present time, our team is working on closing close to £10M of new loan facilities for our clients; all will be complete before Christmas, and 90% of this money will come from the mainstream banks.
It’s really interesting also that the banks’ appetite to get business done has seen our team receive offers on the same deal from more than one bank on a number of occasions. All of this simply means that business owners have more choice, but terms often vary, so be sure to give us a shout if you need some guidance on this.
That’s all for this week,
All the best,
Conor
Conor Devine MRICS
Founding Partner, GDP Partnership